Last Updated on October 16, 2026 1:16 am by INDIAN AWAAZ
Pravin Kumar
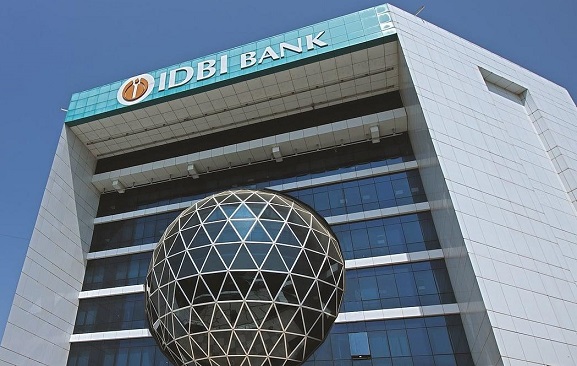
The Union government’s approval of the sale of a 60.72% stake in IDBI Bank to a Fairfax-linked investor group marks one of the most significant banking privatization moves in recent years. Valued at approximately ₹52,878 crore, the transaction will transfer management control of the bank while reducing the combined holding of the government and Life Insurance Corporation of India (LIC) from nearly 91% to 34%. The government has presented the deal as a milestone in financial-sector reform, arguing that greater private-sector participation can improve efficiency, strengthen governance, and reduce the state’s role in commercial banking.
Yet the transaction raises broader questions that extend well beyond the headline sale price. IDBI Bank’s revival was not solely the result of market forces. At a time when the lender was burdened with massive bad loans, mounting losses and regulatory restrictions, public institutions stepped in with capital support and management intervention. Over the past several years, the bank’s financial position has improved dramatically, transforming it from a stressed institution under the Reserve Bank of India’s Prompt Corrective Action framework into a profitable and significantly healthier lender.
This turnaround creates a legitimate public-policy question: when taxpayers and public institutions bear the costs and risks of rescuing a financial institution, how should the benefits of that recovery be measured and distributed? Is the sale price alone sufficient to determine whether the transaction serves the public interest, or should the calculation also include the value created through public investment, future earnings forgone, and the social role that a public-sector bank performs in the economy?
The debate is not fundamentally about whether privatization is good or bad. It is about transparency, valuation and accountability. Before concluding that the IDBI Bank sale represents a successful reform, the government must demonstrate not only what it stands to gain from the transaction, but also why transferring control today delivers greater public benefit than retaining ownership in a transformed and financially stronger bank.
This is particularly important because the IDBI transaction is likely to become a benchmark for future banking disinvestment initiatives. The manner in which its costs, benefits and long-term consequences are evaluated could shape the broader debate over the future role of the state in India’s banking sector for years to come.
A Bank Rescued from Crisis
IDBI Bank’s financial troubles were serious. Bad loans and years of losses had pushed it into a difficult position. In May 2017, the Reserve Bank of India placed the bank under its Prompt Corrective Action (PCA) framework, imposing restrictions on its operations. These restrictions were removed in March 2021 after the bank’s financial position improved.
The government and LIC provided capital support to help stabilise the bank. Public resources played an important role when the risks were high and the bank’s future was uncertain.
The picture has changed considerably since then. IDBI Bank’s gross non-performing asset (NPA) ratio fell from 31.78% in September 2018 to 2.32% in March 2026. This is a substantial improvement and reflects a major turnaround in the bank’s financial condition.
That turnaround raises an obvious question. If public capital was needed to rescue the bank, how will the public benefit from the institution’s improved financial health? Is transferring control to a private owner the only logical next step after a successful recovery? Or could the bank have continued operating under public ownership, generating profits and contributing to the wider public banking system?
These are not arguments against private investment. They are questions about whether the government has properly assessed all the available options before making a decision of this scale.
Sale Proceeds Are Not the Same as Public Benefit
The government’s case for the sale needs to be examined beyond the difference between the money invested and the amount received from the transaction.
A public asset cannot be valued only by comparing its historical investment cost with its sale price. Its current business, future earnings, market position and wider public role must also be considered.
If IDBI Bank continues to earn profits in the coming years, its shareholders could benefit from those earnings through dividends and an increase in the value of their holdings. Future profits are never guaranteed, and a bank may need additional capital, technology investment and stronger risk management. These risks must also be taken into account.
The real question, therefore, is not whether privatisation is inherently good or bad. It is whether the government has transparently compared the likely benefits and costs of retaining public ownership with those of transferring control to a private investor.
The public deserves to know the basis on which this decision was taken. A detailed assessment should explain the bank’s valuation, expected future earnings, investment requirements, risks and the long-term implications of the sale.
Was the Bank Sold at the Right Price?
The price itself deserves public scrutiny. The approved transaction values the shares at ₹81 each. According to the government, the successful bid was above the specified price of ₹75.99 per share.
A competitive bidding process is important, but it does not automatically establish that the public received the maximum possible value. A bank’s market share price and the long-term value of a controlling stake are not necessarily the same.
The public should therefore be told how the valuation was conducted. Did the assessment take into account the bank’s future earnings, assets, liabilities, business risks and the benefits that may arise from a change in control? What assumptions were used? Were alternative ownership scenarios examined?
These questions do not imply that the transaction was necessarily undervalued. They underline the need for evidence before making a definitive claim that the deal represents the best financial outcome for the public.
Banking Is More Than a Business
A bank is not merely a financial institution that accepts deposits and provides loans. It also connects farmers, small businesses, salaried workers and ordinary households to the wider economy. Access to affordable banking services, rural branches, credit for smaller borrowers and the ability to support public welfare programmes all have wider social value.
It would be wrong to assume that a private owner will automatically abandon these responsibilities. Equally, it would be wrong for the government to leave their future entirely unexplained.
What conditions will protect banking services in rural and underserved areas? How will the interests of employees be safeguarded? What arrangements will ensure that small borrowers continue to have access to credit? How will customer service and grievance redressal be monitored?
Regulatory oversight will continue to matter, but the government should also explain whether clear, measurable obligations have been built into the transaction and how compliance will be monitored.
After the sale, the government and LIC will retain a combined 34% stake. Public ownership will not disappear entirely, but control of the bank will shift. That makes transparency about future responsibilities even more important.
IDBI Could Set the Tone for Future Bank Privatisation
The implications of this deal extend beyond IDBI Bank. In the Union Budget for 2021, the government announced its intention to privatise two public-sector banks. However, names discussed by experts or in the media should not be treated as an officially confirmed list of banks for sale.
Even so, the IDBI transaction is likely to become an important reference point in future debates over public-sector banking. If the government presents this deal as a successful example of reform, it should also publish a clear assessment of its financial results and its impact on the public interest.
The argument that the government should focus on education, healthcare, infrastructure and other public priorities rather than managing every commercial enterprise has merit. Private investment may bring fresh capital, technology and management expertise. The sale could also provide substantial funds to the public exchequer.
But these arguments do not, by themselves, establish that the timing, price and conditions of a particular sale are appropriate. A sound policy principle does not guarantee that every individual transaction will produce the best possible result.
Government Must Put the Full Account Before the Public
The central issue is not opposition to private capital. It is the need to explain the decision to transfer control of an institution whose recovery depended significantly on public resources.
The government should make the following information available:
- The dates and actual cost of capital invested in the bank.
- The valuation of the government’s and LIC’s holdings, including the effect of changes in the value of money over time.
- The dividends received and the expected future earnings from retaining the stakes.
- The bank’s future capital requirements, business risks and investment needs.
- The valuation methodology, assumptions and comparison with alternative ownership options.
- The safeguards for employees, small borrowers, rural banking and other public responsibilities.
In a democracy, the government has the authority to make decisions about public assets. But that authority comes with a duty to explain how those decisions serve the public interest. A major transaction cannot be fully justified through a press release, a headline sale figure or broad claims about reform. It must also stand up to scrutiny based on evidence, transparent valuation and clearly defined public benefits.
The sale of IDBI Bank is therefore more than a disinvestment transaction. It is a test of an economic approach in which public capital helps stabilise a struggling institution, while private ownership becomes the preferred option after its financial position improves.
If the decision truly serves the public interest, the government should have no reason to withhold the full account of its costs, benefits and long-term consequences.
The question is not simply how much IDBI Bank is being sold for. The real question is this: without a complete assessment of public investment, future earnings and social responsibilities, how can the government establish that the deal is in the public interest?