Last Updated on October 23, 2026 11:59 pm by INDIAN AWAAZ
OUR CORRESPONDENT
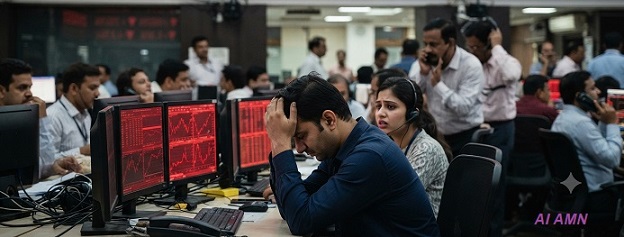
Indian equities endured a difficult week as renewed foreign selling, rising crude oil prices, weak global cues, and sharp corrections in mid- and small-cap counters erased the optimism generated by the previous week’s rally. The benchmark indices closed lower for the fourth consecutive session on Friday, with investors turning increasingly cautious amid geopolitical tensions and concerns about inflationary pressures from higher energy prices.
For the week ended October 23, the BSE Sensex declined by about 1,605 points (2.1%), while the NSE Nifty 50 lost roughly 546 points (2.4%), ending at 73,123.83 and 22,600, respectively. The sell-off was much sharper outside the benchmark indices, with mid-cap and small-cap stocks suffering heavy losses.
Benchmarks Reverse Previous Week’s Gains
The market entered the week with expectations that the previous week’s strong rebound would continue. The rally had been driven largely by information technology stocks and domestic institutional buying. However, sentiment turned negative almost immediately as profit-taking emerged and investors reacted to a combination of higher crude prices, disappointing earnings from some companies, and persistent foreign institutional investor (FII) selling.
On Monday, October 19, the Sensex plunged nearly 876 points, while the Nifty slipped below the 22,900 mark as banking and IT stocks came under pressure. Concerns over rising Brent crude prices and their potential impact on inflation and corporate margins added to the weakness.
Although select sessions witnessed attempts at recovery, the broader trend remained negative throughout the week. By Friday, both major indices had registered four consecutive days of losses, reflecting growing risk aversion among market participants.
Midcaps and Smallcaps Bear the Brunt
The most striking feature of the week was the steep correction in the broader market. According to market reports, the mid-cap index fell around 6%, while the small-cap index declined nearly 7%, marking one of the sharpest weekly setbacks for these segments in recent years.
Market breadth remained decisively negative. On Friday alone, declining stocks significantly outnumbered advancing shares, highlighting the depth of the correction and suggesting that selling was not confined to a handful of sectors.
Investors appeared increasingly concerned about stretched valuations in several high-growth counters. Analysts also pointed to the unwinding of leveraged positions and a shift toward safer, large-cap names amid growing uncertainty.
Rising Crude Oil Emerges as Major Concern
One of the biggest headwinds for Dalal Street this week was the sharp rise in crude oil prices. Brent crude approached $114 per barrel, raising concerns about India’s import bill, inflation trajectory, and corporate profitability.
Higher oil prices generally impact sectors such as aviation, paints, chemicals, logistics, and automobiles, while also increasing macroeconomic risks. The surge in crude was linked to geopolitical tensions in West Asia, which weighed on investor sentiment globally.
Foreign Investors Continue to Exit
FII activity remained another major source of pressure. Market participants closely monitored institutional flows throughout the week, as foreign investors continued to reduce exposure to Indian equities. On October 22 alone, FIIs were reported to have sold shares worth approximately ₹3,459 crore, while domestic institutional investors (DIIs) provided partial support through purchases. [moneycontrol.com]
Although domestic funds have continued to absorb some of the selling, analysts believe sustained FII outflows could keep volatility elevated in the near term.
Sectoral Performance
Sector performance was mixed, with most indices ending the week in negative territory.
Banking stocks remained under pressure following mixed quarterly earnings and concerns over margins. Private lenders were among the week’s notable laggards, contributing significantly to benchmark losses.
Metal stocks also witnessed substantial selling, reflecting both global growth concerns and risk-off sentiment. Realty and PSU banking shares likewise underperformed.
The relative bright spot remained the information technology sector. While IT shares could not escape the broader correction, they generally outperformed several other sectors and helped limit losses in the benchmark indices. Investors continued to evaluate quarterly earnings from leading technology companies for signs of improving demand and stability in global technology spending.
Earnings Take Center Stage
Corporate earnings played an increasingly important role in shaping stock-specific moves during the week. Several companies witnessed sharp reactions following quarterly results, with investors becoming highly selective.
Stocks such as JSW Steel, Shriram Finance, and others experienced notable volatility after earnings announcements and management commentary. Meanwhile, some consumer-oriented companies also faced pressure after reporting results that disappointed market expectations.
The earnings season is expected to remain a key market driver in the coming weeks as investors assess the impact of input costs, consumer demand, and global economic conditions on corporate profitability.
Market Capitalisation Takes a Hit
The broad-based correction translated into a substantial erosion of investor wealth. Estimates suggest that the market capitalisation of BSE-listed companies declined by more than ₹16 lakh crore during the week, while some reports placed the decline even higher depending on the measurement period used.
The decline underscores the intensity of the correction, particularly in broader market segments where losses significantly exceeded those seen in the benchmark indices.
Outlook for Next Week
Looking ahead, investors are expected to closely track four key factors:
- Corporate earnings announcements, especially from heavyweight companies.
- Crude oil prices, which have become a major macroeconomic concern.
- FII and DII investment flows, which will indicate risk appetite.
- Global market sentiment, including developments in major economies and geopolitical hotspots.
Technical analysts suggest that the Nifty’s ability to hold crucial support zones around the lower 22,000 region will be closely watched. Continued weakness in broader markets could keep volatility elevated, while improving earnings and stabilising crude prices may help restore confidence.
Conclusion
After a strong recovery in the previous week, Indian equities suffered a sharp setback during October 19-23. Rising oil prices, renewed foreign selling, global uncertainty, and weakness in mid- and small-cap stocks overshadowed positive earnings developments in select sectors. While the long-term domestic economic story remains intact, the week’s trading highlighted the market’s sensitivity to global risks and institutional flows. For now, investors appear to be shifting toward quality large-cap names while awaiting clearer signals from earnings, crude oil markets, and global macroeconomic developments.
Useful links: https://www.nseindia.com | https://www.bseindia.com | https://www.rbi.org.in